The price system is a decentralized mechanism that relies on the forces of supply and demand to determine the prices of goods and services in a market. It operates without central planning or direct government control, allowing individuals and firms to make independent decisions about production, consumption, and exchange.
Key Components
Functions of the Price System
The price system performs several essential functions in a market economy:
Advantages of the Price System
The price system offers several advantages that contribute to the efficiency and effectiveness of market economies:
Limitations and Criticisms
While the price system offers many advantages, it is not without limitations and criticisms:
Role of Government
Governments often intervene in market economies to address some of the limitations and challenges associated with the price system. Government interventions may include:
Conclusion
The price system is a fundamental mechanism in economics that determines prices through the interaction of supply and demand forces. It plays a vital role in resource allocation, coordination, and the functioning of market economies.
Strengths
✓The price system offers several advantages that contribute to the efficiency and effectiveness of market economies:
Limitations
✗Consumers have a wide range of choices and can select products that best meet their needs and preferences.
✗While the price system offers many advantages, it is not without limitations and criticisms:
When Not To Use
▲While the price system offers many advantages, it is not without limitations and criticisms:
Real-World Examples
Target
Quick Answers
What are the functions of the price system?
The price system performs several essential functions in a market economy:
What are the advantages of the price system?
The price system offers several advantages that contribute to the efficiency and effectiveness of market economies:
What are the limitations and criticisms?
While the price system offers many advantages, it is not without limitations and criticisms:
Key Insight
The price system is a fundamental mechanism in economics that determines prices through the interaction of supply and demand forces. It plays a vital role in resource allocation, coordination, and the functioning of market economies. While it offers numerous advantages, including efficiency and flexibility, it is not without limitations and criticisms, such as income inequality and externalities.
Exec Package + Claude OS Master Skill | Business Engineer Founding Plan
FourWeekMBA x Business Engineer | Updated 2026
The price system is a decentralized mechanism that relies on the forces of supply and demand to determine the prices of goods and services in a market. It operates without central planning or direct government control, allowing individuals and firms to make independent decisions about production, consumption, and exchange.
Key components of the price system include:
Prices: The prices of goods and services are determined by the interaction of buyers (demand) and sellers (supply) in the marketplace. These prices reflect the relative scarcity and value of goods and help allocate resources efficiently.
Markets: Markets serve as the arenas where buyers and sellers come together to exchange goods and services. Markets can take various forms, including physical locations like stock exchanges, online platforms, and informal settings.
Supply and Demand: Supply represents the quantity of a good or service that producers are willing and able to offer for sale at various prices, while demand represents the quantity that consumers are willing and able to purchase at different prices. The equilibrium price is where supply equals demand.
Competition: Competition among producers and consumers helps regulate prices and encourages efficiency. Firms compete to attract customers by offering better products, lower prices, or both.
Price Signals: Prices serve as signals to producers and consumers. When the price of a good increases, it signals that it is relatively scarce, prompting producers to increase supply and consumers to reduce demand. Conversely, when prices fall, it signals abundance.
Functions of the Price System
The price system performs several essential functions in a market economy:
1. Resource Allocation
Prices guide the allocation of resources by signaling where they are most needed. When the price of a good rises, it indicates increased demand or scarcity, prompting producers to allocate more resources to its production. Conversely, when prices fall, resources are reallocated to other goods and services.
2. Efficient Production
Prices encourage producers to operate efficiently and minimize production costs. Firms that can produce goods at lower costs have a competitive advantage and can offer lower prices to consumers.
3. Incentives
Prices provide incentives for both producers and consumers. High prices motivate producers to increase supply, while low prices incentivize consumers to purchase more. This dynamic helps maintain equilibrium in the market.
4. Information
Prices convey information about the value and quality of goods and services. Consumers use prices as indicators of quality and value when making purchasing decisions.
5. Coordination
The price system coordinates the actions of millions of producers and consumers, ensuring that resources are distributed and products are delivered to where they are needed most. It enables complex supply chain — as explored in how AI is restructuring the traditional value chain — s to function smoothly.
6. Innovation
Higher prices for innovative products encourage firms to invest in research and development, leading to technological advancements and new products.
Advantages of the Price System
The price system offers several advantages that contribute to the efficiency and effectiveness of market economies:
1. Efficiency
Prices allocate resources efficiently by directing them to where they are most valued and needed. Resources flow to industries and products that consumers demand the most.
2. Flexibility
The price system is flexible and responsive to changes in supply and demand conditions. Prices adjust quickly to reflect shifts in preferences, technological advancements, and changes in resource availability.
3. Consumer Choice
Consumers have a wide range of choices and can select products that best meet their needs and preferences. Prices provide information about product quality and value, aiding in decision-making.
4. Innovation
The prospect of earning higher prices incentivizes firms to innovate, improve product quality, and develop new technologies.
5. Self-Regulation
The price system allows markets to self-regulate. If there is excess demand for a product, prices rise, encouraging increased supply. Conversely, if there is excess supply, prices fall, reducing production.
6. Competition
Prices encourage competition among producers, leading to greater efficiency, lower prices, and improved product quality.
7. Adaptability
The price system can adapt to changing economic conditions, ensuring that resources are allocated optimally even in times of crisis or uncertainty.
Limitations and Criticisms
While the price system offers many advantages, it is not without limitations and criticisms:
1. Inequality
The price system can lead to income inequality, as individuals and firms with greater resources can take advantage of market opportunities and accumulate wealth more easily.
2. Externalities
Market prices do not always reflect the full social costs and benefits of production and consumption. Externalities, such as pollution or positive spillover effects, may not be adequately considered in market transactions.
3. Imperfect Competition
In some markets, competition may be imperfect, leading to higher prices and reduced consumer choice. Monopolies and oligopolies can exploit their market power.
4. Short-Term Focus
Prices may prioritize short-term gains over long-term sustainability and social well-being. Firms may prioritize profit maximization at the expense of environmental or social considerations.
5. Income Effects
Price changes can have income effects, impacting the purchasing power of consumers. For example, rising prices can reduce the real income of consumers, affecting their overall welfare.
6. Public Goods
The price system struggles to allocate resources for public goods, which are non-excludable and non-rivalrous. Public goods may be underprovided in a purely market-driven system.
Role of Government
Governments often intervene in market economies to address some of the limitations and challenges associated with the price system. Government interventions may include:
Regulation: Governments regulate markets to ensure fair competition, prevent monopolies, and protect consumers and the environment.
Taxation and Subsidies: Taxes and subsidies can be used to correct externalities and encourage or discourage certain behaviors.
Public Goods Provision: Governments provide public goods and services that the price system may underprovide, such as defense, infrastructure, and education.
Income Redistribution: Taxation and social welfare programs can help reduce income inequality and provide a safety net for those in need.
Conclusion
The price system is a fundamental mechanism in economics that determines prices through the interaction of supply and demand forces. It plays a vital role in resource allocation, coordination, and the functioning of market economies. While it offers numerous advantages, including efficiency and flexibility, it is not without limitations and criticisms, such as income inequality and externalities. Government intervention is often necessary to address these shortcomings and ensure that market outcomes align with societal goals and values. The price system remains a central concept in economics, shaping how goods and services are produced, exchanged, and consumed in modern economies.
Expanded Pricing Strategies Explorer
Pricing Strategy
Description
Key Insights
Cost-Plus Pricing
Markup added to production cost for profit
Ensures costs are covered and provides a predictable profit margin.
Value-Based Pricing
Prices set based on perceived customer value
Aligns prices with what customers are willing to pay for the product or service.
Competitive Pricing
Pricing in line with competitors or undercutting
Helps maintain competitiveness and market share.
Dynamic Pricing
Prices adjusted based on real-time demand
Maximizes revenue by responding to changing market conditions.
Penetration Pricing
Low initial prices to gain market share
Attracts price-sensitive customers and establishes brand presence.
Price Skimming
High initial prices gradually lowered
Capitalizes on early adopters’ willingness to pay a premium.
Bundle Pricing
Multiple products or services as a package
Increases the perceived value and encourages upselling.
Psychological Pricing
Pricing strategies based on psychology
Leverages pricing cues like $9.99 instead of $10 for perceived savings.
Freemium Pricing
Free basic version with premium paid features
Attracts a wide user base and converts some to paying customers.
Subscription Pricing
Recurring fee for ongoing access or service
Creates predictable revenue and fosters customer loyalty.
Skimming and Scanning
Continually adjusting prices based on market dynamics
Adapts to changing market conditions and optimizes pricing.
Promotional Pricing
Temporarily lowering prices for promotions
Encourages short-term purchases and boosts sales volume.
Geographic Pricing
Adjusting prices based on geographic location
Accounts for variations in cost of living and local demand.
Anchor Pricing
High initial price as a reference point
Influences perception of value and makes other options seem more affordable.
Odd-Even Pricing
Prices just below round numbers (e.g., $19.99)
Creates a perception of lower cost and encourages purchases.
Loss Leader Pricing
Offering a product below cost to attract customers
Drives traffic and encourages additional purchases.
Prestige Pricing
High prices to convey exclusivity and quality
Appeals to premium or luxury markets and enhances brand image.
Value-Based Bundling
Combining complementary products for value
Encourages customers to buy more while receiving a perceived discount.
Decoy Pricing
Less attractive third option to influence choice
Guides customers toward a preferred option.
Pay What You Want (PWYW)
Customers choose the price they want to pay
Promotes customer goodwill and can lead to higher payments.
Dynamic Bundle Pricing
Prices for bundled products based on customer choices
Tailors bundles to customer preferences.
Segmented Pricing
Different prices for the same product by segments
Considers diverse customer groups and willingness to pay.
Target Pricing
Prices set based on a specific target margin
Ensures profitability based on specific financial goals.
Loss Aversion Pricing
Emphasizes potential losses averted by purchase
Encourages decision-making by highlighting potential losses.
Membership Pricing
Exclusive pricing for members of loyalty programs
Fosters customer loyalty and membership growth.
Seasonal Pricing
Price adjustments based on seasonal demand
Matches pricing to fluctuations in consumer behavior.
FOMO Pricing (Fear of Missing Out)
Limited-time discounts or deals
Creates urgency and encourages purchases.
Predatory Pricing
Low prices to deter competitors or drive them out
Strategic pricing to gain market dominance.
Price Discrimination
Different prices to different customer segments
Capitalizes on varying willingness to pay.
Price Lining
Different versions of a product at different prices
Catering to various customer preferences.
Quantity Discount
Discounts for bulk or volume purchases
Encourages larger orders and repeat business.
Early Bird Pricing
Lower prices for early adopters or advance buyers
Rewards early commitment and generates initial sales.
Late Payment Penalties
Additional fees for late payments
Encourages timely payments and revenue collection.
Bait-and-Switch Pricing
Attracting with a low-priced item, then upselling
Uses attractive deals to lure customers to higher-priced options.
Group Buying Discounts
Discounts for purchases made by a group or community
Encourages collective buying and customer loyalty.
Lease or Rent-to-Own Pricing
Lease with an option to purchase later
Provides flexibility and ownership choice for customers.
Bid Pricing
Customers bid on products or services
Prices determined by customer demand and willingness to pay.
Quantity Surcharge
Charging a fee for purchasing below a certain quantity
Encourages larger orders and higher sales.
Referral Pricing
Discounts or incentives for customer referrals
Leverages word-of-mouth marketing and customer networks.
Tiered Pricing
Multiple price levels based on features or benefits
Appeals to customers with varying needs and budgets.
Charity Pricing
Donating a portion of sales to a charitable cause
Aligns with corporate social responsibility and attracts conscious consumers.
Behavioral Pricing
Price adjustments based on customer behavior
Customizes pricing based on customer interactions and preferences.
Mystery Pricing
Prices hidden until the product is added to the cart
Encourages customer engagement and commitment.
Variable Cost Pricing
Prices adjusted based on variable production costs
Reflects cost changes and maintains profitability.
Demand-Based Pricing
Prices set based on demand patterns and peak periods
Maximizes revenue during high-demand periods.
Cost Leadership Pricing
Competing by offering the lowest prices in the market
Focuses on cost efficiencies and price competitiveness.
Asset Utilization Pricing
Pricing based on the utilization of assets
Optimizes revenue for assets like rental cars or hotel rooms.
Markup Pricing
Fixed percentage or dollar amount added as profit
Ensures consistent profit margins on products.
Value Pricing
Premium pricing for products with unique value
Attracts customers willing to pay more for exceptional features.
Sustainable Pricing
Pricing emphasizes environmental or ethical considerations
Appeals to conscious consumers and supports sustainability goals.
The idea of a market economy first came from classical economists, including David Ricardo, Jean-Baptiste Say, and Adam Smith. All three of these economists were advocates for a free market. They argued that the “invisible hand” of market incentives and profit motives were more efficient in guiding economic decisions to prosperity than strict government planning.
Positive economics is concerned with describing and explaining economic phenomena; it is based on facts and empirical evidence. Normative economics, on the other hand, is concerned with making judgments about what “should be” done. It contains value judgments and recommendations about how the economy should be.
When there is an increased price of goods and services over a long period, it is called inflation. In these times, currency shows less potential to buy products and services. Thus, general prices of goods and services increase. Consequently, decreases in the purchasing power of currency is called inflation.
Asymmetric information as a concept has probably existed for thousands of years, but it became mainstream in 2001 after Michael Spence, George Akerlof, and Joseph Stiglitz won the Nobel Prize in Economics for their work on information asymmetry in capital markets. Asymmetric information, otherwise known as information asymmetry, occurs when one party in a business transaction has access to more information than the other party.
Autarky comes from the Greek words autos (self)and arkein (to suffice) and in essence, describes a general state of self-sufficiency. However, the term is most commonly used to describe the economic system of a nation that can operate without support from the economic systems of other nations. Autarky, therefore, is an economic system characterized by self-sufficiency and limited trade with international partners.
Creative destruction was first described by Austrian economist Joseph Schumpeter in 1942, who suggested that capital was never stationary and constantly evolving. To describe this process, Schumpeter defined creative destruction as the “process of industrial mutation that incessantly revolutionizes the economic structure from within, incessantly destroying the old one, incessantly creating a new one.” Therefore, creative destruction is the replacing of long-standing practices or procedures with more innovative, disruptive practices in capitalist markets.
Happiness economics seeks to relate economic decisions to wider measures of individual welfare than traditional measures which focus on income and wealth. Happiness economics, therefore, is the formal study of the relationship between individual satisfaction, employment, and wealth.
An oligopsony is a market form characterized by the presence of only a small number of buyers. These buyers have market power and can lower the price of a good or service because of a lack of competition. In other words, the seller loses its bargaining power because it is unable to find a buyer outside of the oligopsony that is willing to pay a better price.
The term “animal spirits” is derived from the Latin spiritus animalis, loosely translated as “the breath that awakens the human mind”. As far back as 300 B.C., animal spirits were used to explain psychological phenomena such as hysterias and manias. Animal spirits also appeared in literature where they exemplified qualities such as exuberance, gaiety, and courage. Thus, the term “animal spirits” is used to describe how people arrive at financial decisions during periods of economic stress or uncertainty.
State capitalism is an economic system where business and commercial activity is controlled by the state through state-owned enterprises. In a state capitalist environment, the government is the principal actor. It takes an active role in the formation, regulation, and subsidization of businesses to divert capital to state-appointed bureaucrats. In effect, the government uses capital to further its political ambitions or strengthen its leverage on the international stage.
The boom and bust cycle describes the alternating periods of economic growth and decline common in many capitalist economies. The boom and bust cycle is a phrase used to describe the fluctuations in an economy in which there is persistent expansion and contraction. Expansion is associated with prosperity, while the contraction is associated with either a recession or a depression.
The paradox of thrift was popularised by British economist John Maynard Keynes and is a central component of Keynesian economics. Proponents of Keynesian economics believe the proper response to a recession is more spending, more risk-taking, and less saving. They also believe that spending, otherwise known as consumption, drives economic growth. The paradox of thrift, therefore, is an economic theory arguing that personal savings are a net drag on the economy during a recession.
In simplistic terms, the circular flow model describes the mutually beneficial exchange of money between the two most vital parts of an economy: households, firms and how money moves between them. The circular flow model describes money as it moves through various aspects of society in a cyclical process.
Trade deficits occur when a country’s imports outweigh its exports over a specific period. Experts also refer to this as a negative balance of trade. Most of the time, trade balances are calculated based on a variety of different categories.
A market type is a way a given group of consumers and producers interact, based on the context determined by the readiness of consumers to understand the product, the complexity of the product; how big is the existing market and how much it can potentially expand in the future.
Rational choice theory states that an individual uses rational calculations to make rational choices that are most in line with their personal preferences. Rational choice theory refers to a set of guidelines that explain economic and social behavior. The theory has two underlying assumptions, which are completeness (individuals have access to a set of alternatives among they can equally choose) and transitivity.
The peer-to-peer (P2P) economy is one where buyers and sellers interact directly without the need for an intermediary third party or other business. The peer-to-peer economy is a business model where two individuals buy and sell products and services directly. In a peer-to-peer company, the seller has the ability to create the product or offer the service themselves.
The term “knowledge economy” was first coined in the 1960s by Peter Drucker. The management consultant used the term to describe a shift from traditional economies, where there was a reliance on unskilled labor and primary production, to economies reliant on service industries and jobs requiring more thinking and data analysis. The knowledge economy is a system of consumption and production based on knowledge-intensive activities that contribute to scientific and technical innovation.
In a command economy, the government controls the economy through various commands, laws, and national goals which are used to coordinate complex social and economic systems. In other words, a social or political hierarchy determines what is produced, how it is produced, and how it is distributed. Therefore, the command economy is one in which the government controls all major aspects of the economy and economic production.
How do you protect your rights as a worker? Who is there to help defend you against unfair and unjust work conditions? Both of these questions have an answer, and it’s a solution that many are familiar with. The answer is a labor union. From construction to teaching, there are labor unions out there for just about any field of work.
The bottom of the pyramid is a term describing the largest and poorest global socio-economic group. Franklin D. Roosevelt first used the bottom of the pyramid (BOP) in a 1932 public address during the Great Depression. Roosevelt noted that – when talking about the ‘forgotten man:’ “these unhappy times call for the building of plans that rest upon the forgotten, the unorganized but the indispensable units of economic power.. that build from the bottom up and not from the top down, that put their faith once more in the forgotten man at the bottom of the economic pyramid.”
Glocalization is a portmanteau of the words “globalization” and “localization.” It is a concept that describes a globally developed and distributed product or service that is also adjusted to be suitable for sale in the local market. With the rise of the digital economy, brands now can go global by building a local footprint.
Market fragmentation is most commonly seen in growing markets, which fragment and break away from the parent market to become self-sustaining markets with different products and services. Market fragmentation is a concept suggesting that all markets are diverse and fragment into distinct customer groups over time.
The L-shaped recovery refers to an economy that declines steeply and then flatlines with weak or no growth. On a graph plotting GDP against time, this precipitous fall combined with a long period of stagnation looks like the letter “L”. The L-shaped recovery is sometimes called an L-shaped recession because the economy does not return to trend line growth. The L-shaped recovery, therefore, is a recession shape used by economists to describe different types of recessions and their subsequent recoveries. In an L-shaped recovery, the economy is characterized by a severe recession with high unemployment and near-zero economic growth.
Comparative advantage was first described by political economist David Ricardo in his book Principles of Political Economy and Taxation. Ricardo used his theory to argue against Great Britain’s protectionist laws which restricted the import of wheat from 1815 to 1846. Comparative advantage occurs when a country can produce a good or service for a lower opportunity cost than another country.
The Easterlin paradox was first described by then professor of economics at the University of Pennsylvania Richard Easterlin. In the 1970s, Easterlin found that despite the American economy experiencing growth over the previous few decades, the average level of happiness seen in American citizens remained the same. He called this the Easterlin paradox, where income and happiness correlate with each other until a certain point is reached after at least ten years or so. After this point, income and happiness levels are not significantly related. The Easterlin paradox states that happiness is positively correlated with income, but only to a certain extent.
In Economics, Economies of Scale is a theory for which, as companies grow, they gain cost advantages. More precisely, companies manage to benefit from these cost advantages as they grow, due to increased efficiency in production. Thus, as companies scale and increase production, a subsequent decrease in the costs associated with it will help the organizationscale further.
In Economics, a Diseconomy of Scale happens when a company has grown so large that its costs per unit will start to increase. Thus, losing the benefits of scale. That can happen due to several factors arising as a company scales. From coordination issues to management inefficiencies and lack of proper communication flows.
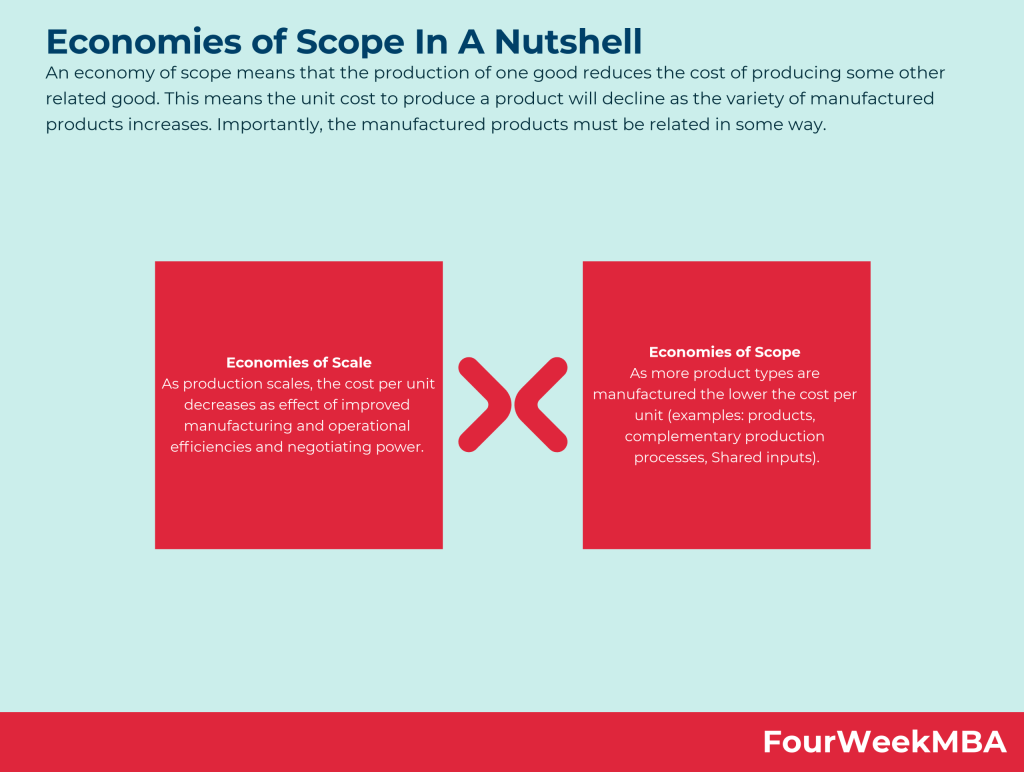
An economy of scope means that the production of one good reduces the cost of producing some other related good. This means the unit cost to produce a product will decline as the variety of manufactured products increases. Importantly, the manufactured products must be related in some way.
Price sensitivity can be explained using the price elasticity of demand, a concept in economics that measures the variation in product demand as the price of the product itself varies. In consumer behavior, price sensitivity describes and measures fluctuations in product demand as the price of that product changes.
The key components of Price system include Cost-Plus Pricing, Value-Based Pricing, Competitive Pricing, Dynamic Pricing, Penetration Pricing. Cost-Plus Pricing: Markup added to production cost for profit Value-Based Pricing: Prices set based on perceived customer value
Prices guide the allocation of resources by signaling where they are most needed. When the price of a good rises, it indicates increased demand or scarcity, prompting producers to allocate more resources to its production. Conversely, when prices fall, resources are reallocated to other goods and services.
How do you apply Price system in practice?
Prices encourage producers to operate efficiently and minimize production costs. Firms that can produce goods at lower costs have a competitive advantage and can offer lower prices to consumers.
What are the advantages and limitations of Price system?
Prices provide incentives for both producers and consumers. High prices motivate producers to increase supply, while low prices incentivize consumers to purchase more. This dynamic helps maintain equilibrium in the market.
What are the functions of the price system?
The price system performs several essential functions in a market economy:
What are the key components of Price system?
The key components of Price system include Functions of the Price System, Advantages of the Price System, Limitations and Criticisms, Role of Government. Functions of the Price System: The price system performs several essential functions in a market economy:
Frequently Asked Questions
What is Price system?
The price system is a decentralized mechanism that relies on the forces of supply and demand to determine the prices of goods and services in a market. It operates without central planning or direct government control, allowing individuals and firms to make independent decisions about production, consumption, and exchange.
What are the functions of the price system?
The price system performs several essential functions in a market economy:
What are the key components of Price system?
The key components of Price system include Functions of the Price System, Advantages of the Price System, Limitations and Criticisms, Role of Government, Conclusion. Functions of the Price System: The price system performs several essential functions in a market economy:
Gennaro is the creator of FourWeekMBA, which reached about four million business people, comprising C-level executives, investors, analysts, product managers, and aspiring digital entrepreneurs in 2022 alone | He is also Director of Sales for a high-tech scaleup in the AI Industry | In 2012, Gennaro earned an International MBA with emphasis on Corporate Finance and Business Strategy.
Scroll to Top
Discover more from FourWeekMBA
Subscribe now to keep reading and get access to the full archive.