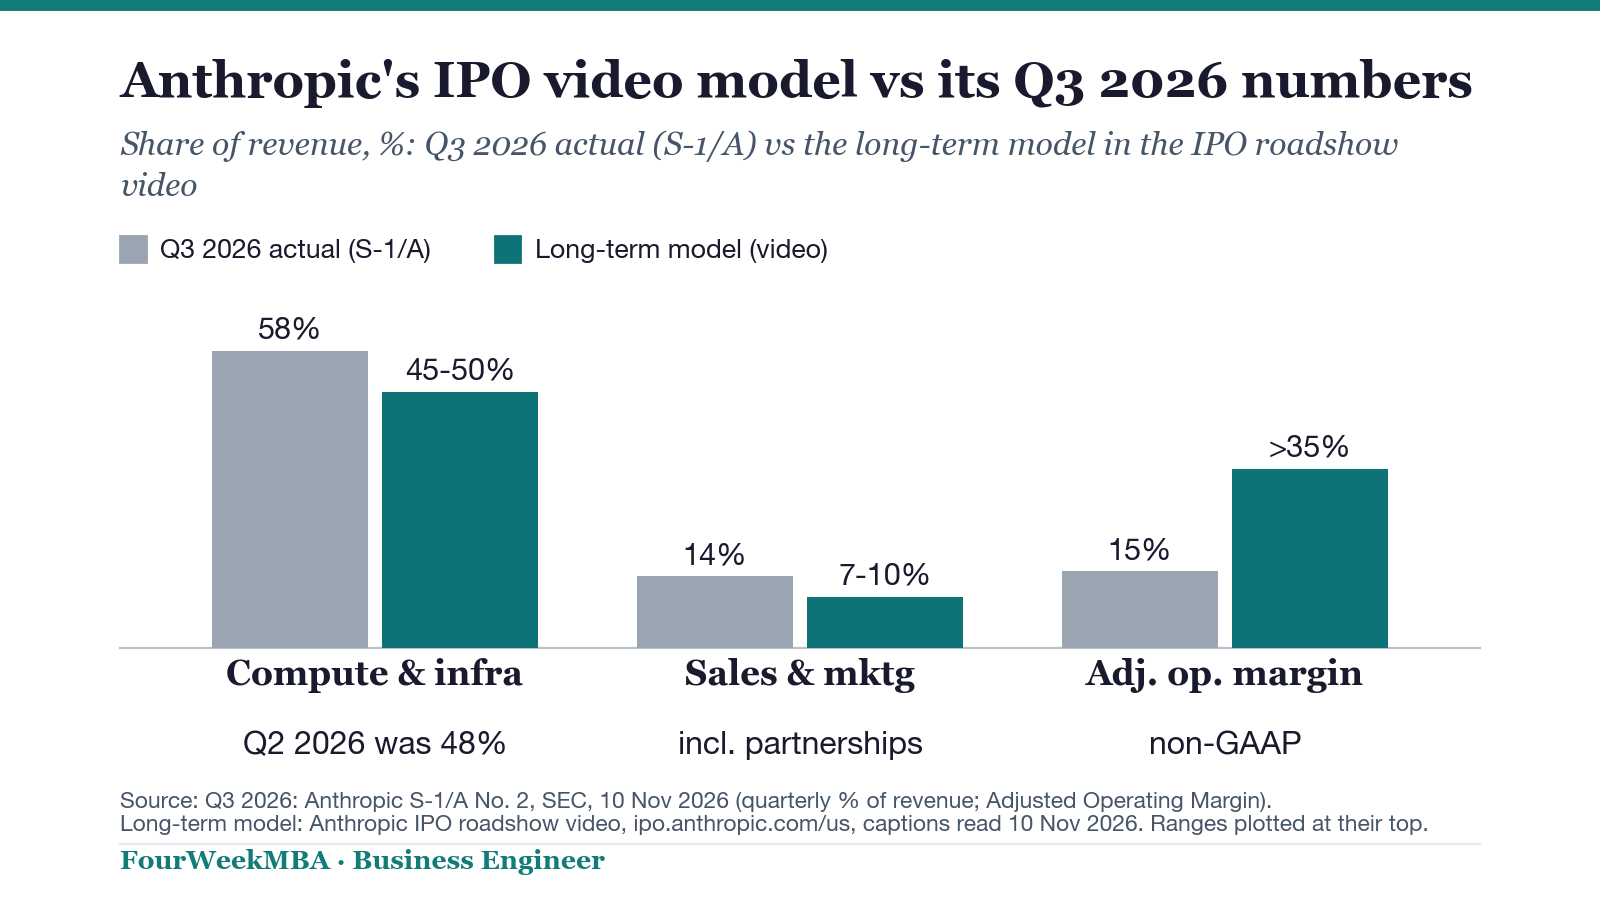
Anthropic has put a roadshow video of about 41 minutes on a website for US investors in its IPO, and the video’s financial segment sets out a long-term model: “We believe Anthropic can deliver adjusted operating margins of more than 35%”, according to the video’s captions. Its S-1/A of 10 November reports an Adjusted Operating Margin of 15% for the third quarter of 2026.
The video also puts compute and infrastructure on a path to “approximately 45 to 50% of revenue”. In the third quarter that line was 58% of revenue, the filing shows, 8 to 13 points above the range, by our arithmetic. In the second quarter it was 48%, inside it. We did not find the long-term model in the S-1/A text, and no free writing prospectus was on EDGAR as of 14:24 UTC.
Business Pill · Tokens per Watt
A short explainer on tokens per watt, a measure of compute efficiency. It teaches the general idea only and does not discuss Anthropic.
The key insight: Anthropic’s IPO roadshow video, on its site for US investors, says the company can deliver adjusted operating margins of more than 35%, with compute and infrastructure at about 45 to 50% of revenue. Its S-1/A shows 15% and 58% for the third quarter of 2026, 8 to 13 points above the compute range, by our arithmetic; the second quarter’s 48% sat inside it.
The captions do not name speakers. The financial segment refers back to earlier speakers as “Tom” and “Paul”. We quote the captions as published, not our own transcription.
After the 35% line, the captions continue: “We see a path for compute and infrastructure expenses to trend towards approximately 45 to 50% of revenue”. On sales: “we expect sales, marketing and partnership costs to trend towards 7 to 10% of revenue, as partner fees become a smaller share of revenue as we scale”.
On the rest of the cost base: “we expect personnel and other operating expenses combined to trend towards 7 to 10% of revenue, as Claude makes our teams more productive and we grow headcount efficiently”.
The video ties the 35% to three drivers: “continued efficiency gains, a greater share of Anthropic Direct capacity, and more of our compute shifting towards inference”. It gives no date for reaching the model.
The S-1/A frames the same cost line without a target: “compute and infrastructure expenses as a percentage of revenue will depend primarily on how our revenue scales relative to our total committed compute cost base”.
Third-quarter 2026 cost lines and Adjusted Operating Margin from Anthropic’s S-1/A of 10 November 2026, against the long-term model in its IPO roadshow video (captions). Ranges are plotted at their top.
What Was Posted on X
ANTHROPIC’S ADJUSTED OPERATING MARGIN SWUNG FROM -221% TO +15% IN 18 MONTHS
Wall St Engine posted at 16:24 UTC on 10 November that Anthropic’s Adjusted Operating Margin swung from −221% to +15% in 18 months, listing seven quarters from Q1 2025 to Q3 2026. All seven figures match the quarterly table in Anthropic’s 10 November S-1/A, set out in the update box on this page.
Some slides from the Anthropic roadshow video
– big emphasis on fungible compute, ability to use compute efficiently and onboard new chips quickly – still very early in agents outside of coding – long-term target of 35% adjusted operating margins
Tanay Jaipuria posted on 11 November at 01:37 UTC four images the post calls slides from Anthropic’s roadshow video, writing of a “long-term target of 35% adjusted operating margins”. The fourth image, titled “Long-term model framework”, shows an adjusted operating margin of 15% in Q3 2026 and “35%+” long-term, with compute and infrastructure at “~45-50%” of revenue long-term against 58% in Q3; those figures match the captions and filing quoted in this piece.
The Video’s Figures Against the Filing
For results, the captions say: “In Q3, we earned nearly $17 billion of revenue, up 12 times year over year. And year to date, we’ve delivered a compute margin of 43%, gross margin of 85%, adjusted operating margin of 12% and positive free cash flow”.
The filing has revenue of $16,956 million for the quarter and a nine-month Adjusted Operating Margin of 12%. It does not report a compute margin in the text we searched. Nine-month compute and infrastructure was $18,808 million on $33,242 million of revenue, 56.6%, so 43.4% is left, by our arithmetic, which matches the video’s 43%.
The gross margin also checks out. The filing does not state one, but its notes group expenses by function: cost of revenue was $4,812 million for the nine months, so 85.5% of revenue is left, by our arithmetic, and 29.4% for the same period of 2025. We did not find a free cash flow figure in the S-1/A text. The filing reports net cash from operating activities of $6.6 billion for the nine months. Less $925 million of property and equipment purchases, that is $5.6 billion, by our arithmetic; the video does not say how it defines free cash flow.
Another line checks out against the filing: “We grew revenue by more than 45x, while computing infrastructure costs grew only 10x”. From the first quarter of 2025 to the third of 2026, revenue rose from $376 million to $16,956 million, 45.1 times, and compute and infrastructure from $944 million to $9,863 million, 10.4 times, by our arithmetic. The same caption says gross margin is “over 85%, up from 29% in the same period of 2025”.
Two more video lines match the filing. Code contributed per engineer is “up 45x relative to the 2024 average” in the video and “over 45 times the average daily volume in the year ended December 31, 2024” in the S-1/A. Claude Cowork’s adoption “has exceeded that of Claude Code at the equivalent point”, the video says; the filing says it “outpaced the adoption Claude Code achieved at the equivalent point”.
Claims That Are Video-Only
Several claims in the captions did not turn up in our search of the S-1/A. On pricing: Opus 5.5 “delivered substantial gains in model capability and 40% lower customer costs. This reduction was margin neutral to us because Opus 5.5 is significantly cheaper to serve”. The filing has the 40% cut in cost per task; we did not find the margin-neutral line.
On costs outside compute: “our entire non-compute expense base, including sales and marketing personnel and other operating expenses, represents a lower percentage of revenue than the median enterprise software company spends on sales and marketing alone”. On output: “In the first nine months of 2026, we shipped 250 models, products and features”.
On chips: “It got Claude running on AMD in just three days with basically no human intervention”. On security, Mozilla “used to fix over 20 security bugs per release, and with Mythos Preview, they identified and fixed 271”.
What Is on the Site
The page lists a founders’ letter, the video in 11 chapters, Q3 2026 highlights, five customer stories and the broker links. The highlights include a “>4x” compute efficiency gain since the first quarter of 2025, measured as “revenue divided by compute and infrastructure expenses in Q3’26 divided by the same ratio in Q1’25”. The filing’s numbers give 4.3 times, by our arithmetic.
Under How to participate, it links Charles Schwab, E*TRADE, Fidelity, Robinhood and SoFi. Its FAQ says the final price “is expected to be set on November 18th (EST)” and that shares “are expected to begin publicly trading on November 19th (EST)”. Our roadshow piece had 19 or 20 November; our retail piece covers the allocation.
From London, the US address redirected to a UK page that reads only “More information to come.” We read the US page and the captions through a US-located fetch.
Update (11 Nov): the quarterly path behind the 15%.
The 10 November S-1/A lists Adjusted Operating Margin for seven quarters: (221)% in the first quarter of 2025, (129)%, (93)%, (84)%, (13)% in the first quarter of 2026, 19% in the second and 15% in the third. Over the same quarters revenue went from $376 million to $16,956 million, and Adjusted Operating Income from a loss of $830 million to $2,463 million. The same table was in the 2 November filing.
By our arithmetic, the swing from the first quarter of 2025 to the third quarter of 2026 is 236 percentage points, and the second quarter of 2026 was the first positive quarter. The filing attributes the fall from 19% to 15% primarily to “the $5.0 billion of short-term compute”. GAAP operating margin over the seven quarters went from (249)% to (3)%; the adjusted measure excludes stock-based compensation, non-cash charitable contributions and the Bartz settlement.
The Structural Read
As we read the two documents, the video is where Anthropic states the destination and the filing is where it reports the starting point: the long-term model did not turn up in our search of the S-1/A, which says the compute ratio depends on how revenue scales against a committed cost base.
As we read the quarterly table, the compute ratio is not a one-way line: it fell to 48% in the second quarter and rose to 58% in the third, so a single quarter inside the 45 to 50% range does not show the model is reached.
Anthropic IPO roadshow video (captions), 10 November 2026
“We believe Anthropic can deliver adjusted operating margins of more than 35%”
Three Implications
FOR THE MARGIN Third-quarter Adjusted Operating Margin was 15% and nine-month 12%, the S-1/A shows; the video’s model is more than 35%, with no date given.
FOR COMPUTE Compute and infrastructure was 58% of third-quarter revenue against a 45 to 50% path, 8 to 13 points above, by our arithmetic.
FOR THE FIGURES The video’s 43% compute margin matches 100% less the filing’s nine-month compute ratio of 56.6%, by our arithmetic; its 85% gross margin matches the filing’s nine-month cost of revenue, 85.5%, by our arithmetic.
The framework argues: “The accounting metric (gross margin) and the strategic metric (harness density) are anti-correlated by design.”
As we read it, the roadshow video describes that choice in its own words: efficiency gains are “capital that we get to allocate”, sometimes passed to customers through lower prices and sometimes kept as margin. The framework was published in June and does not discuss the video.
What Is Not Established
The video gives no year for the long-term model, and the 35% is a non-GAAP measure. The S-1/A defines Adjusted Operating Margin as excluding stock-based compensation, non-cash charitable contributions and the Bartz settlement; the video does not define its gross margin or free cash flow. No free writing prospectus was on EDGAR as of 14:24 UTC; the S-1/A filed at 11:29 UTC is the latest filing.
The Great Convergence of Capital, Power, and Geopolitics
This week’s issue: for two years the AI build-out was priced as a supply story, and last week as a credit story. This week it was priced as a permission story, and the answer arrived as a cost, not a ban.
Anthropic’s roadshow video sets out a long-term model the S-1/A text does not: adjusted operating margins above 35%, with compute and infrastructure at about 45 to 50% of revenue. In the third quarter the filing shows 15% and 58%; in the second, compute was 48%.
95,000+ executives read Business Engineer for the AI strategy frameworks cited by ChatGPT, Claude, and Perplexity.
A note on sourcing. Quotations from the roadshow video are from Anthropic’s own captions file, read on 10 November 2026; the site text is from ipo.anthropic.com/us. Filing figures are from Anthropic’s S-1/A filed with the SEC on 10 November 2026; the EDGAR filing list was read at 14:24 UTC. Differences, ratios and percentages are our arithmetic. Anthropic was not contacted for this piece.
Gennaro Cuofano is a CRO and tech executive who has worked in AI since late 2015, starting with bringing NLP, natural-language generation, voice and chatbot products to the marketing industry. His background is in law and finance: he holds a Master's degree in Law and an International MBA with an emphasis on corporate finance (LUISS Business School and the University of San Diego, 2012), and worked as a financial analyst at a real-estate investment firm in San Diego and as an assistant controller. His work focuses on business model strategy, business engineering and, more broadly, structural analysis: how companies make money, read from their own filings. He created FourWeekMBA and leads research there and at The Business Engineer, his newsletter on AI and business strategy, with over 95,000 subscribers and more than 1,000 published analyses. His writing has also appeared on Entrepreneur (for example, How to Digitize a Family Business in Europe) and HackerNoon. Find him on LinkedIn and Substack. See how we source.