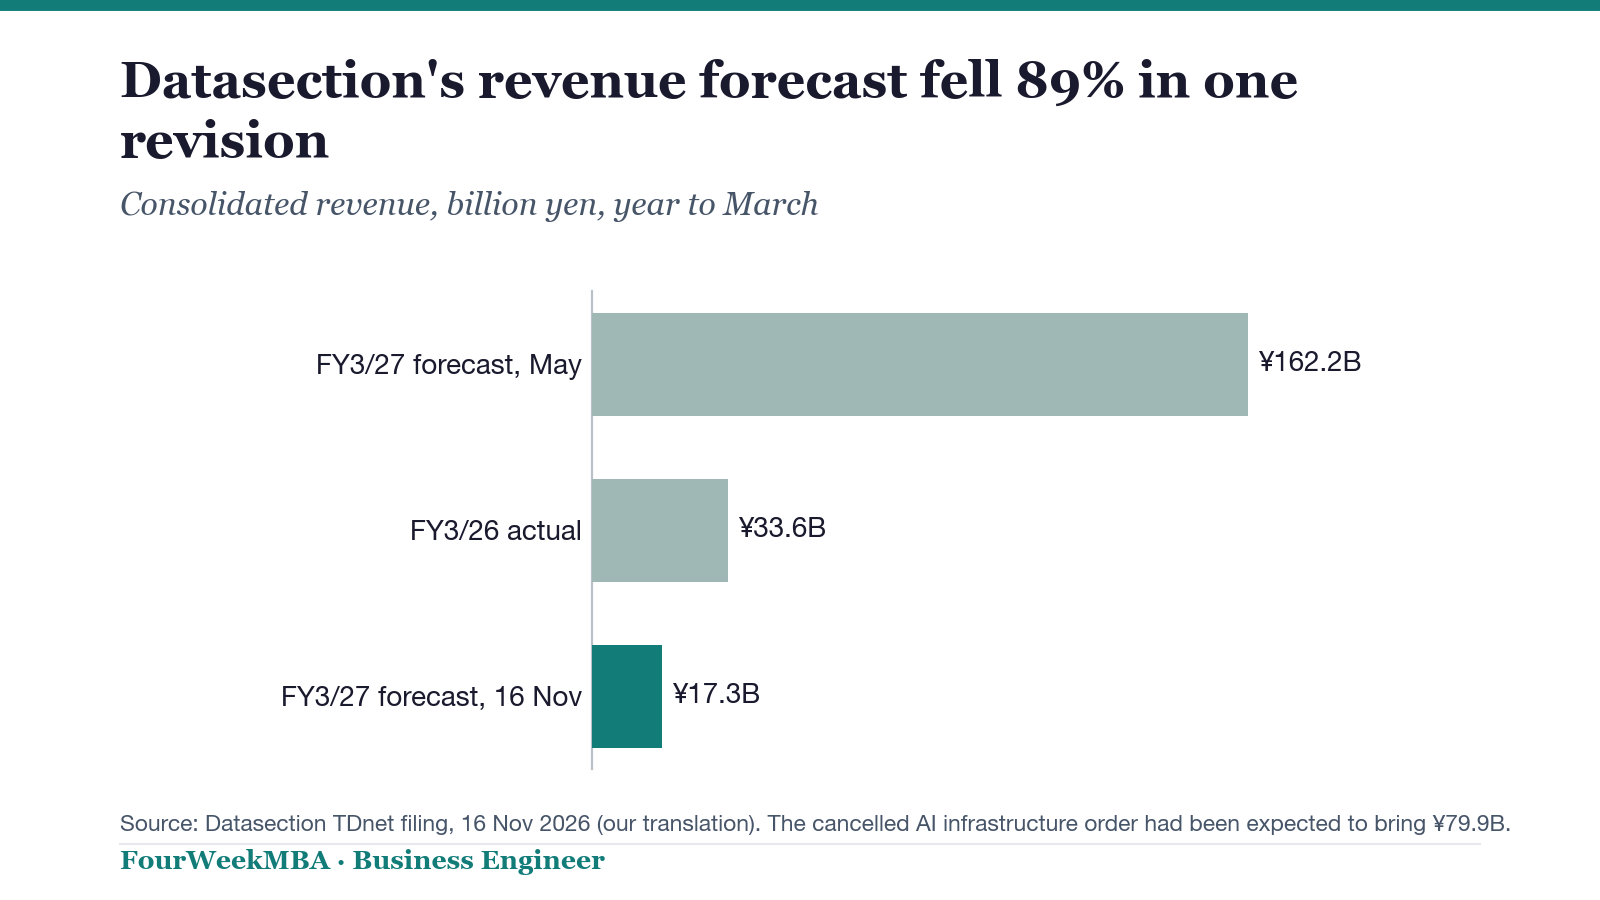
Datasection, a Tokyo-listed GPU data centre operator, cut its revenue forecast for the year to March 2027 by 89.3%, from ¥162.2 billion to ¥17.3 billion, it said in a 16 November filing. An AI infrastructure order it had expected to bring ¥79.9 billion of revenue was cancelled.
Our number: the cancelled order accounts for 55% of the ¥144.9 billion of revenue removed from the forecast, and the only revenue it leaves is a ¥5.6 billion arrangement fee already booked, about 7% of what the order was expected to bring (our arithmetic).
Business Pill · Concentration Explained
An evergreen Business Engineer explainer on concentration risk. It teaches the general idea only and does not discuss Datasection.
The key insight: Datasection cut its revenue forecast 89.3% to ¥17.3 billion after a ¥79.9 billion AI infrastructure order was cancelled, leaving one operating overseas data centre as 59% of what remains (our arithmetic).
The company now expects operating profit of ¥4.9 billion instead of ¥24.8 billion (down 80.2%), adjusted EBITDA of ¥10.2 billion instead of ¥58.2 billion, and a net loss of ¥1.5 billion instead of a net profit of ¥8.7 billion, according to the filing as we translate it. Revenue for the year to March 2026 was ¥33.6 billion, so the new forecast is about half of last year’s (our arithmetic).
Datasection says it now counts only projects with a high probability of revenue this year: ¥10.2 billion from one overseas AI data centre that has already started operating, 59% of the new forecast (our arithmetic). One domestic and two overseas data centre projects due to ramp from July were delayed, it says. Other large prospective deals are progressing more slowly than expected.
Datasection cut its revenue forecast for the year to March 2027 from ¥162.2 billion to ¥17.3 billion, below last year’s ¥33.6 billion. Source: Datasection filing, 16 November 2026.
The Australian Data Centre
A second filing the same day says that at one overseas facility, talks with the customer dragged on over changes including a switch from Nvidia B200 to B300 servers. The start of operation was significantly delayed, and on 31 August the property owner gave notice to terminate the facility-use contract. On 16 November, Datasection and its subsidiary Datasection Australia Pty. Ltd. decided to accept the termination and seek a replacement property or compensation. It booked a ¥2.75 billion lease cancellation loss and a ¥314 million provision for long-term telecom contracts.
The filings do not name the customer. In December 2025, Chosun Biz summarised a Financial Times report: a “large client” had signed a “$1.2 billion” contract with Datasection through a third party, and, citing sources, “the client is Tencent”. It added that Datasection planned a second data centre in Sydney using B300s, with Tencent reported as the main client.
The Balance Sheet
Datasection’s interim report shows cash and equivalents of ¥397 million at the start of the period, 31 March 2026, and ¥6.69 billion at 30 September, after warrant exercises raised capital. Total assets rose by ¥29.6 billion in the half to ¥58.2 billion, mainly GPU servers and leased data centre space, the report says.
In a thread on 18 November, SemiAnalysis said “~$773M of GPU purchase commitments are still unpaid, funded mostly by warrants struck at ¥1,250”. It put the stock at ¥891. We have not verified those two figures in the filings.
As we read the filings, the forecast cut is a concentration story: one order was worth almost half of the original revenueplan.
As we read them, the Australian termination shows how a hardware generation change, B200 to B300, can stall a data centre project and its lease.
SemiAnalysis on X, 18 Nov 2026
“This is the “Japanese neocloud” that the FT reported is effectively a Tencent datacenter: Chinese offtake, Nvidia Blackwell GPUs, Japanese flag.”
Three Implications
FOR GPU LANDLORDS The filing shows a single cancelled order removing ¥79.9 billion of expected revenue.
FOR DATA CENTRE OWNERS The Australian property owner terminated a facility-use contract after operation was delayed, the filing says.
FOR LENDERS AND INVESTORS SemiAnalysis says GPU purchase commitments remain unpaid; we have not verified that figure.
What Is Not Established
The filings do not name the customer behind the cancelled order or the Australian facility, or say why the order was cancelled beyond the delays described. SemiAnalysis also said the stock went limit-down; we did not check the trading data. The English renderings of the Japanese filings are our translation.
This article is for information only and is not investment advice.
This Week In The AI Supercycle
AI Lost Its Central Banker, the Lab Oligopoly, and the Future of Open Source
This week’s issue: the Nvidia leadership change, read as the AI build-out losing its central banker: who now finances the GPU landlords, backstops the data centres and sponsors open models, and why two labs are becoming the bank.
One cancelled order took ¥79.9 billion out of Datasection’s year, its revenue forecast is now 89% lower, and the company is counting on a single operating data centre for most of what remains.
A note on sourcing. Forecast figures, reasons and the Australian lease termination are from Datasection’s two TDnet filings of 16 November 2026 and its interim report, in our translation from Japanese. The Tencent link is attributed to the Financial Times via Chosun Biz’s December 2025 summary; the unpaid GPU commitments, warrant strike, share price and limit-down are SemiAnalysis’s figures, not verified by us. The 55%, 7%, 59% and one-half shares are our arithmetic. We did not contact Datasection.
Gennaro Cuofano is a CRO and tech executive who has worked in AI since late 2015, starting with bringing NLP, natural-language generation, voice and chatbot products to the marketing industry. His background is in law and finance: he holds a Master's degree in Law and an International MBA with an emphasis on corporate finance (LUISS Business School and the University of San Diego, 2012), and worked as a financial analyst at a real-estate investment firm in San Diego and as an assistant controller. His work focuses on business model strategy, business engineering and, more broadly, structural analysis: how companies make money, read from their own filings. He created FourWeekMBA and leads research there and at The Business Engineer, his newsletter on AI and business strategy, with over 95,000 subscribers and more than 1,000 published analyses. His writing has also appeared on Entrepreneur (for example, How to Digitize a Family Business in Europe) and HackerNoon. Find him on LinkedIn and Substack. See how we source.